The Stablecoin Debit Card Revolution: Why It’s Not Just About Payments
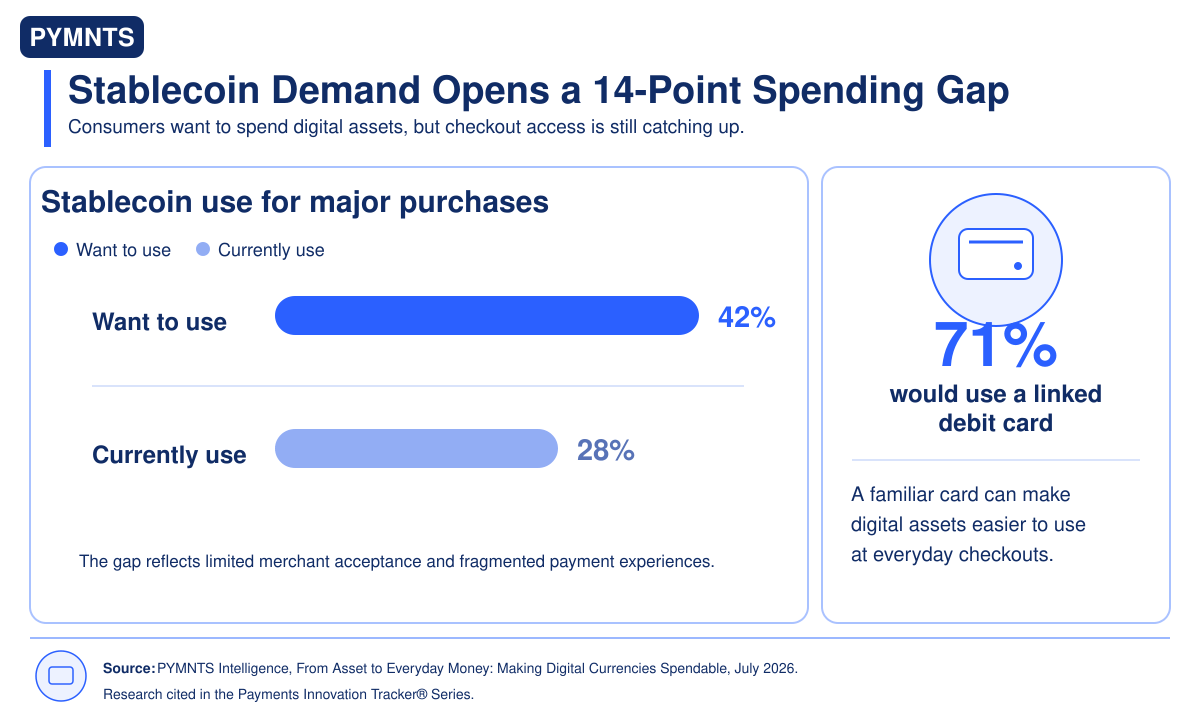
There’s a quiet revolution brewing in the world of digital assets, and it’s not about Bitcoin hitting another all-time high or a new DeFi protocol launching. It’s about something far more mundane—yet, in my opinion, far more transformative. According to a recent report by PYMNTS Intelligence, 71% of stablecoin holders would spend their holdings using a debit card. On the surface, this might seem like a niche statistic, but if you take a step back and think about it, it’s a seismic shift in how we perceive digital currencies.
The Familiarity Factor: Why Debit Cards Are the Trojan Horse of Crypto Adoption
What makes this particularly fascinating is the role of familiarity in driving adoption. Stablecoins, by design, are meant to be less volatile than other cryptocurrencies, pegging their value to stable assets like the U.S. dollar. But even with this stability, they’ve struggled to become a go-to payment method. Why? Because, as the report highlights, the gap between owning stablecoins and using them for everyday purchases is still wide.
Here’s where debit cards come in. Seventy-one percent of stablecoin holders say they’d use a linked debit card to spend their assets. Personally, I think this is a game-changer. It’s not about reinventing the wheel; it’s about putting a new kind of fuel into the same engine. Debit cards are a tool consumers already trust and understand. By linking them to stablecoins, we’re essentially bypassing the need for mass education on blockchain, wallets, or gas fees. What this really suggests is that the future of crypto adoption might not be about creating entirely new systems but about integrating digital assets into existing ones.
Trust in Banks and FinTechs: The Unseen Advantage
One thing that immediately stands out is the trust consumers place in their existing financial providers. Seventy-seven percent of respondents said they’d open a crypto or stablecoin wallet through their bank or FinTech app if given the option. This is huge. What many people don’t realize is that the biggest barrier to crypto adoption isn’t technology—it’s trust. Consumers are wary of handing their money over to unfamiliar platforms or interfaces.
From my perspective, this is where traditional banks and FinTechs have a golden opportunity. By offering stablecoin wallets within their existing apps, they can demystify digital assets and make them feel less like a speculative investment and more like everyday money. It’s a win-win: consumers get the security of a trusted institution, and banks get to stay relevant in a rapidly evolving financial landscape.
The Broader Implications: Beyond Consumer Checkout
If you zoom out, the implications of this trend go far beyond individual spending habits. Monthly crypto card spending grew 15-fold from 2023 to 2025, reaching an annualized rate of $18 billion. That’s not pocket change. Stablecoins are also making inroads in cross-border business payments, where their speed and cost-efficiency are solving real-world problems.
But here’s the kicker: the barriers to adoption are still significant. Limited merchant acceptance, transaction costs, and fraud concerns are holding people back. This raises a deeper question: Can the debit card solution really bridge this gap? I believe it can, but only if it’s part of a broader ecosystem that addresses these pain points. Real-time conversion, lower fees, and seamless integration with existing payment networks will be key.
The Psychological Shift: From Investment to Utility
A detail that I find especially interesting is the shift in how people perceive stablecoins. Forty-two percent of holders want to use them for major purchases, but only 28% currently do. This 14-point gap isn’t just about infrastructure—it’s about mindset. Stablecoins are no longer just a hedge against inflation or a speculative asset; they’re becoming a tool for everyday life.
This psychological shift is crucial. It’s the difference between holding an asset because it might appreciate in value and using it because it’s convenient. If stablecoins can become as frictionless as swiping a debit card, we’re looking at a future where digital currencies are indistinguishable from traditional money—at least in the eyes of the consumer.
The Future: A Hybrid Financial World
So, where does this leave us? In my opinion, we’re on the cusp of a hybrid financial world where digital and traditional currencies coexist seamlessly. Debit cards are just the beginning. As more banks and FinTechs integrate stablecoins into their offerings, we’ll likely see a cascade of innovations—from real-time cross-border payments to programmable money.
But here’s the provocative part: What happens when stablecoins become so ubiquitous that they start to replace traditional fiat currencies? It’s a question that central banks and governments are already grappling with. From my perspective, the debit card revolution isn’t just about making payments easier—it’s about redefining what money is in the digital age.
Final Thoughts
The idea that 71% of stablecoin holders would use a debit card to spend their assets isn’t just a statistic—it’s a signal. It tells us that consumers are ready for digital currencies, but on their terms. They want familiarity, trust, and convenience. The financial institutions that can deliver these will be the ones to lead the charge.
Personally, I think we’re witnessing the early stages of a paradigm shift. Stablecoins aren’t just an alternative to traditional money—they’re its evolution. And the humble debit card? It might just be the key to unlocking their full potential.